Why Did My Minnesota Home Insurance Go Up? 2024–2026 Data and What to Check
Updated November 6, 2026
Updated October 2026
The short answer: Minnesota homeowners premiums rose sharply in 2024 and 2025 as insurers responded to years of costly hail and windstorms and higher rebuilding costs. But your own increase can also come from changes to your policy itself: a higher dwelling limit, a new wind/hail deductible, different roof terms, a lost discount or a recent claim. Compare your old and new declarations pages line by line before deciding what to do.
Three numbers that mean three different things
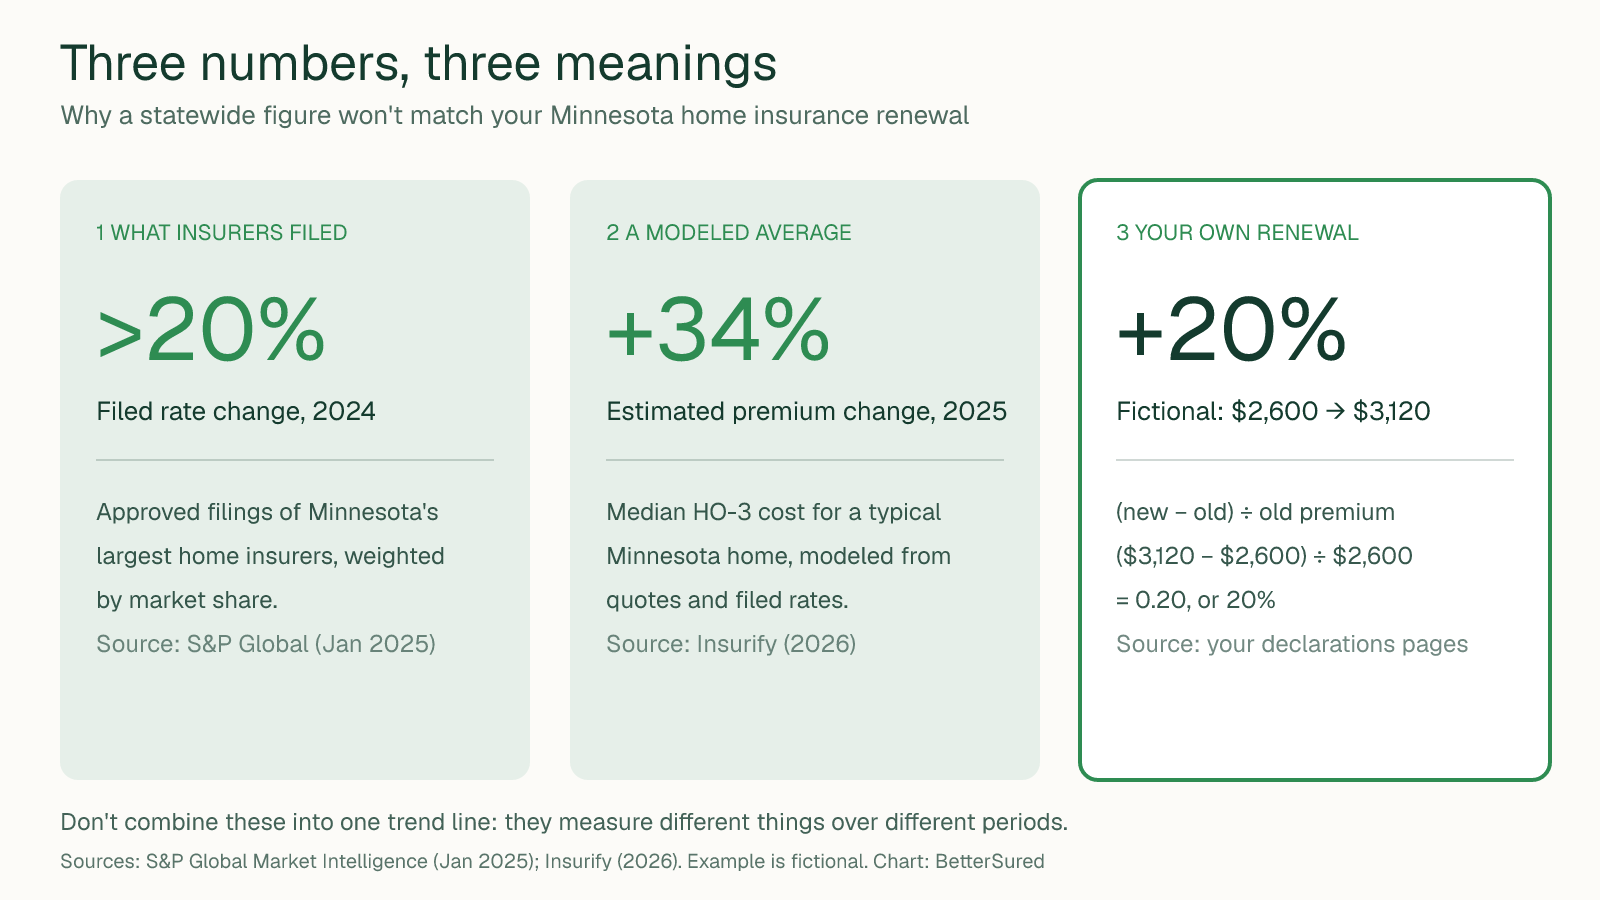
The graphic at the top of this page sets out the problem: you will see several "Minnesota home insurance went up" figures, and none of them is your renewal.
| Figure | What it measures | Period | Source |
|---|---|---|---|
| Above 20% | Effective rate change in approved filings by Minnesota's largest home insurers, weighted by market share | 2024 | S&P Global |
| +34% (to about $3,530 a year) | Modeled median cost of a standard HO-3 policy for a typical Minnesota home, from quotes and filed rates | End of 2024 to end of 2025 | Insurify |
| Your percentage | The change in what you pay, for the coverage your insurer is now offering you | Your policy term | Your declarations pages |
The first two are useful context. S&P Global's figure tells you insurers were approved for large increases; Insurify's estimate, which assumes about $407,000 of dwelling coverage, a 2% hail deductible, good credit and no recent claims, describes a hypothetical typical policy. Insurify also reports that Minnesota's average rose about 64% over two years, the largest two-year increase of any state, and projects a smaller rise of about 4% by the end of 2026. These are estimates. They do not predict any one household's price, and they should not be stitched together into a single trend line.
Calculate your own increase
Use the annual premium on each declarations page (not a monthly escrow amount, which can include taxes and shortage adjustments):
(new annual premium − old annual premium) ÷ old annual premium = your percentage change
Fictional example: a St. Paul homeowner paid $2,600 last year and the renewal shows $3,120. ($3,120 − $2,600) ÷ $2,600 = 0.20, a 20% increase. Before deciding whether that is "a lot," the next step is to see whether the coverage changed too.
The market-wide reasons
Hail and wind losses
Minnesota's biggest homeowners risk is severe convective storms: hail, straight-line winds and tornadoes. The May 19, 2022 hailstorm alone, which hit Minneapolis, St. Paul, the northern suburbs and central Washington County, caused an estimated $2.6 billion in damage, according to the Minnesota DNR. Insurify reports that Minnesota home insurers paid about $158 for every $100 of premium in 2022, a loss that shows up in later rate filings.
Rebuilding costs
Premiums are tied to the cost to rebuild your home, not what it would sell for. When labor and materials cost more, insurers raise the dwelling limit and the rate.
It is not only the weather
Your premium also reflects your insurer's own claims experience, expenses and competitive position, plus factors about you, such as claims history and, in Minnesota, credit-based insurance scores where the insurer uses them. Two neighbors with the same insurer can see different increases.
Policy-level reasons your bill changed
These are the changes you can actually see on your declarations page:
- A higher dwelling limit (Coverage A). Many policies raise this automatically each year to keep pace with rebuilding costs. More coverage costs more, but cutting it below rebuild cost can leave you underinsured.
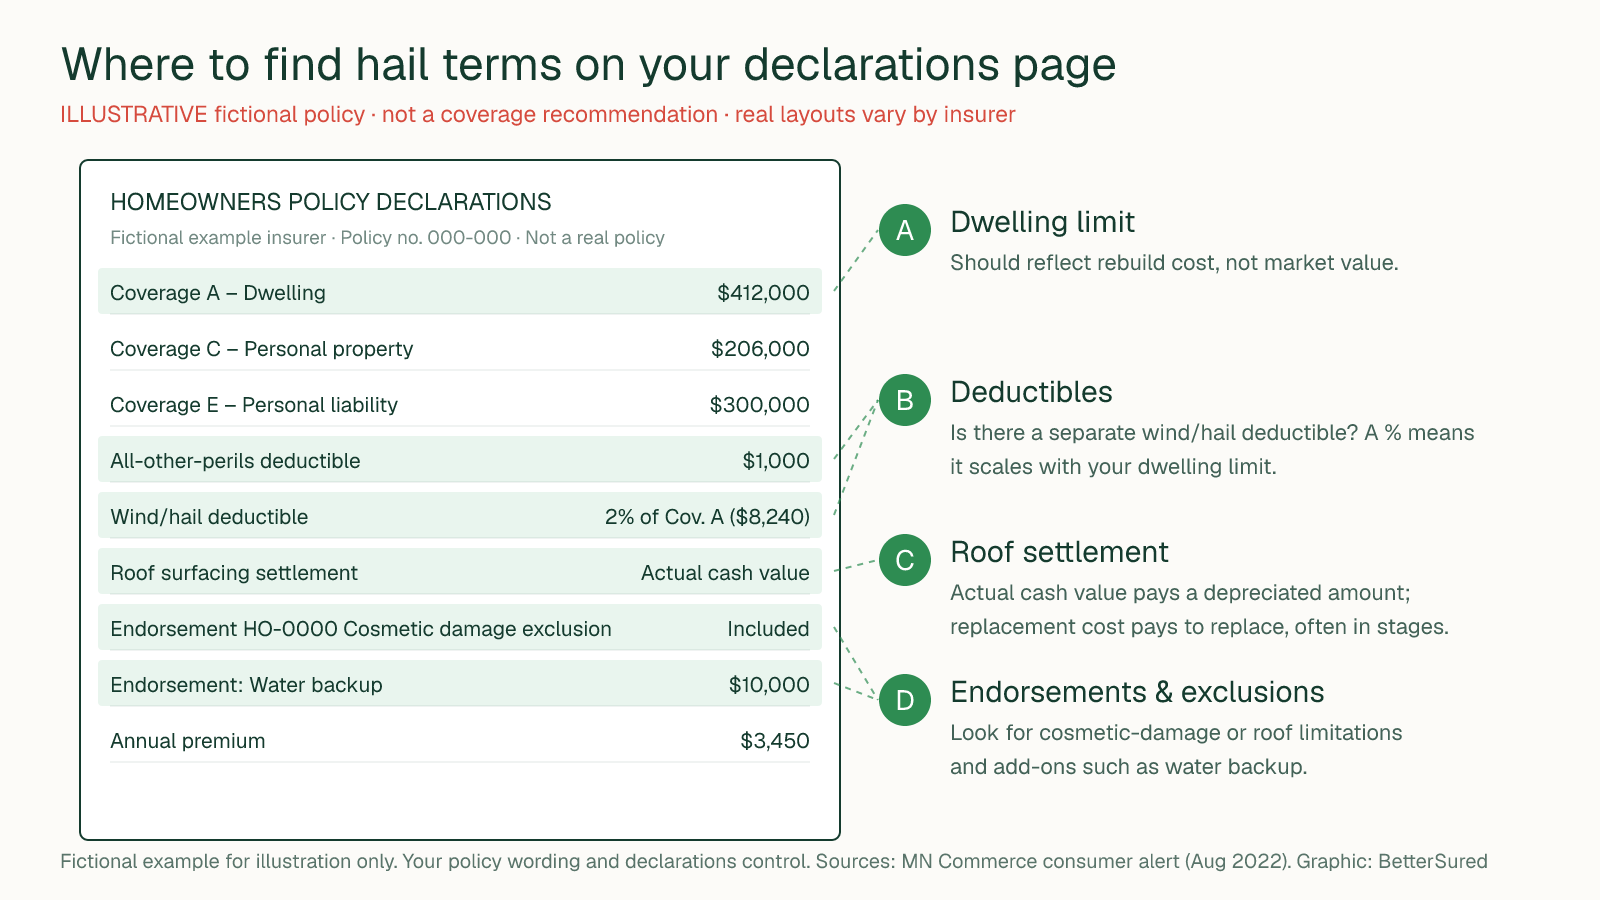
- A new or different wind/hail deductible. The Minnesota Department of Commerce has warned that some policies now carry a separate deductible for wind and hail, either a flat amount or a percentage such as 1% or more of the home's replacement value. On a $400,000 dwelling limit, 1% is $4,000.
- Roof settlement terms. Some policies now pay for roof damage at actual cash value (depreciated) rather than replacement cost, or limit coverage for cosmetic hail damage that does not let water in. Commerce notes state law does not address these cosmetic exclusions, so the wording in your policy controls.
- Endorsements added or removed. Water backup, scheduled jewelry or other add-ons change the price.
- Discounts that dropped off. A lost bundle, claims-free or new-roof discount can raise the total.
- A recent claim. Claims can affect pricing for several years. Our guide on when to file a claim explains the trade-off.
Renewal review checklist
Put last year's and this year's declarations pages side by side and check each line. This checklist is free to print or share with credit to BetterSured.
| Check | What to look for |
|---|---|
| Annual premium | Calculate your percentage change with the formula above. |
| Coverage A (dwelling) | Did it rise? Does it reflect today's rebuild cost? |
| Other structures, personal property, loss of use | Did any limits change? Are they still a percentage of Coverage A? |
| Personal liability | Same limit as last year? Is it enough for your assets? |
| All-other-perils deductible | Same dollar amount? |
| Wind/hail deductible | New? Flat or a percentage? What is it in dollars? |
| Roof settlement | Replacement cost or actual cash value? Any roof age schedule? |
| Endorsements and exclusions | Any new form numbers, especially cosmetic damage or roof limitations? |
| Discounts | Bundle, claims-free, security, new-roof and paid-in-full credits still applied? |
| Renewal notice | Read any letter describing coverage changes; ask your agent about anything unclear. |
Compare equivalent options
If the increase is not explained by more coverage, it may be worth getting quotes. The key is to compare matching home coverage: the same dwelling limit, liability, deductibles and roof terms. A cheaper quote that adds a 2% wind/hail deductible or switches your roof to actual cash value is not like-for-like.
Shopping does not always lower the bill. Across the Minnesota market, insurers have been raising rates at the same time, so the best available price may be close to your renewal. That is still useful to know. For a sense of cadence, see how often to shop for insurance.
When to contact an agent or Commerce
- Your agent or insurer can explain each line of the renewal, whether a discount was removed, and what your options are for deductibles and roof coverage.
- An independent agent can quote several insurers at once and point out coverage differences.
- The Minnesota Department of Commerce Consumer Services Center (651-539-1600 or 800-657-3602) can help if you have a complaint about how an insurer handled your policy or a claim. If you received a non-renewal rather than an increase, see our guide on what to do after a non-renewal.
Related Minnesota guides
- Minnesota home and auto insurance cost guide
- Review Minnesota wind and hail coverage before storm season
- How to document hail damage and start a claim
- Condo and townhome insurance in Minnesota
Compare quotes on the same coverage
BetterSured reads the declarations page you upload so quotes match your current limits and deductibles, then vetted local independent brokers compete to quote that coverage. Brokers pay BetterSured for these requests, and your details go only to the brokers who quote you. Not every insurer is represented, quotes depend on underwriting, and a lower price is not guaranteed.
Related guides
Water Damage vs. Flood Insurance: What Your Standard Home Policy Covers
Actual Cash Value vs. Replacement Cost: Understanding Your Property Coverage
Condo Insurance (HO-6) vs. HOA Master Policy: What Coverage Do You Actually Need?
Twin Cities Hail Damage: Check These Home Insurance Terms Before Storm Season