Minnesota Winter Car Insurance: What Covers a Crash, Deer Strike, or Hail Damage?
Updated November 6, 2026
Updated October 2026. General information; your policy and insurer decide how a claim is handled.
The short answer: In Minnesota, damage to your own car from an icy-road crash is usually a collision claim; hitting a deer or hail damage is usually a comprehensive claim; damage you cause to someone else's car is covered by your liability; and injuries are paid first by personal injury protection (PIP), regardless of fault. Collision and comprehensive are optional, so check you have them, and know your deductibles, before winter.
Five winter scenarios: which coverage may apply
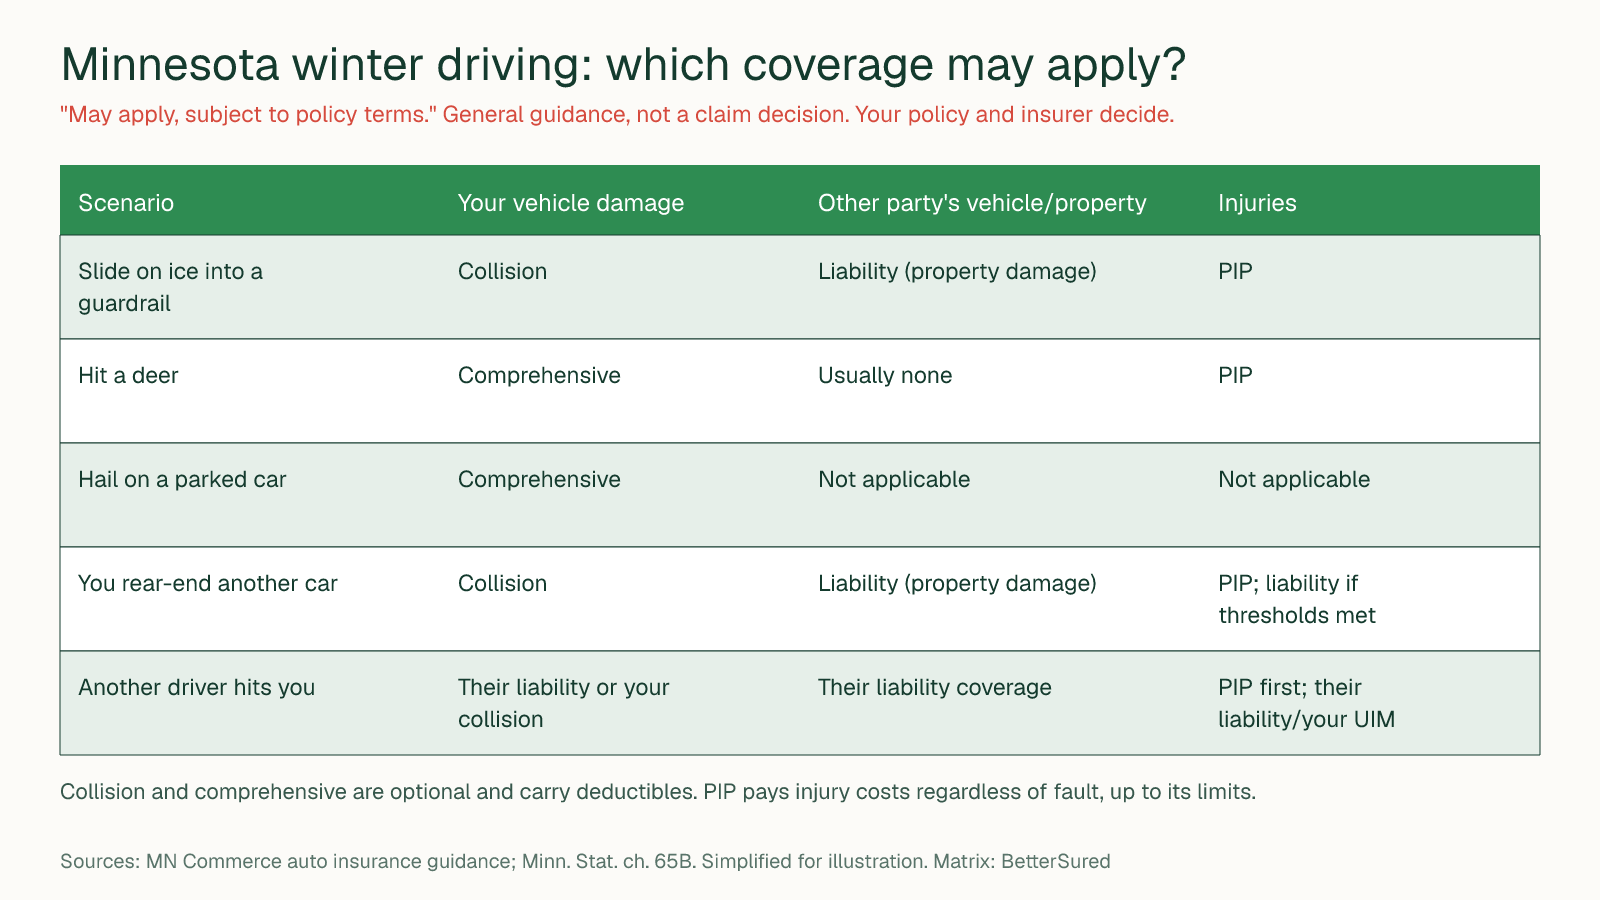
The matrix at the top of this page and the table below show which coverage may apply, subject to policy terms. This is general guidance, not a claim decision.
| Scenario | Your vehicle damage | Other party's vehicle or property | Injuries |
|---|---|---|---|
| You slide on ice into a guardrail | Collision | Your property damage liability (for the guardrail) | PIP |
| You hit a deer | Comprehensive | Usually none | PIP |
| Hail dents your parked car | Comprehensive | Not applicable | Not applicable |
| You rear-end another car on a slick road | Collision | Your property damage liability | PIP; your bodily injury liability if the other person's claim meets legal thresholds |
| Another driver slides into you | The other driver's liability, or your collision | The other driver's liability coverage | PIP first; then the other driver's liability or your underinsured motorist coverage |
Coverage definitions follow the Minnesota Department of Commerce and Minnesota's No-Fault Act. Have your agent or insurer confirm how your policy applies.
The scenarios in more detail
Sliding on ice
Weather does not change who pays. If your car hits another vehicle, a guardrail, a curb or a snowbank, damage to your car falls under collision, minus your deductible. Damage you cause to someone else's property falls under your property damage liability, and that claim can affect your future premiums. Minnesota's minimum property damage limit is only $10,000 per accident.
Hitting a deer
Hitting an animal is generally covered by comprehensive, not collision. One common wrinkle: if you swerve to avoid a deer and hit a tree or another car instead, insurers usually treat that as a collision claim. Safety officials generally advise not swerving sharply for a deer, because the swerve can be more dangerous than the impact.
Hail on a parked car
Hail damage to your car is a comprehensive claim. Because hail can hit thousands of Twin Cities vehicles in one storm, comprehensive claims were the biggest driver of Minnesota's recent auto insurance increases, according to the Minneapolis Fed. The same storms damage roofs; see our Twin Cities hail guide for the home side.
Injuries
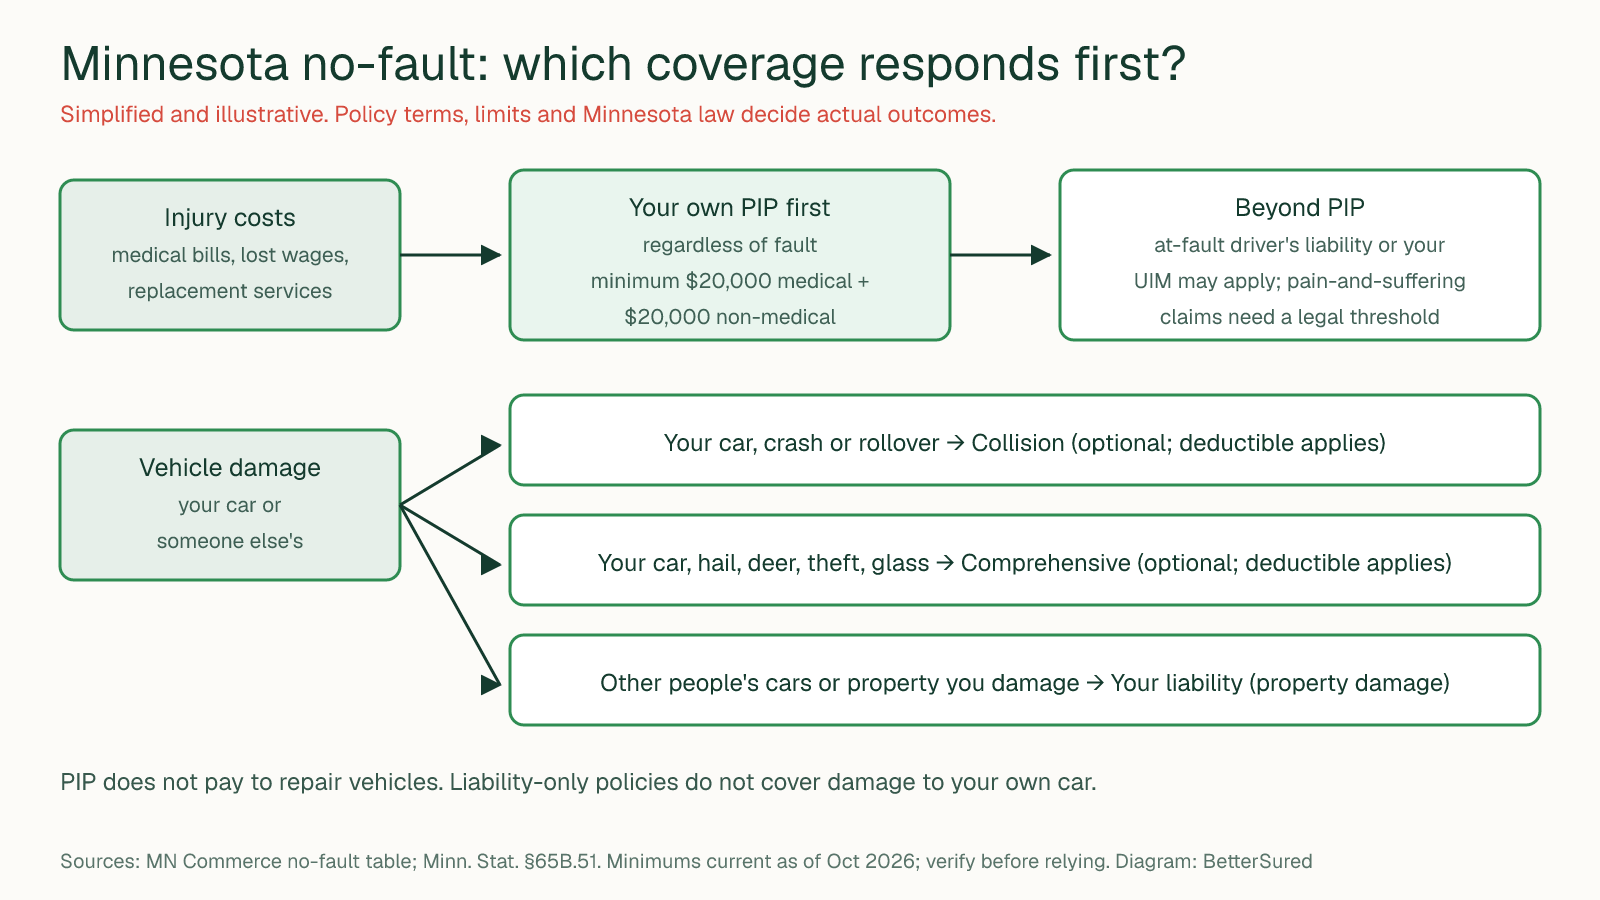
Your PIP pays you and your passengers' medical bills and certain other losses first, no matter who caused the crash, up to its limits (minimum $20,000 medical and $20,000 non-medical per person). Our Minnesota no-fault explainer covers what PIP does and does not pay.
A deductible reminder
Collision and comprehensive each have their own deductible, and they can be different amounts. If your comprehensive deductible is $1,000 and the deer damage is $1,400, the claim pays about $400. Some policies offer lower comprehensive deductibles or full glass coverage. Our guide to deductibles explains the trade-off with your premium.
What to document after an incident
- Get to a safe place first; call 911 if anyone is hurt or a vehicle is blocking traffic.
- Photograph the vehicles, the road conditions, the location and any animal or debris, if it is safe to do so.
- Exchange names, insurance details and vehicle information with any other driver.
- Note the date, time and weather, and keep towing and repair receipts.
- Report the claim to your insurer promptly, following your policy's requirements. Commerce has more on what to do after an accident and auto storm damage.
Policy review before winter
| Done | Check |
|---|---|
| ☐ | Do you have collision and comprehensive on each car you'd want repaired? |
| ☐ | What are your collision and comprehensive deductibles in dollars? |
| ☐ | Are your liability limits above the 30/60/10 minimum, and enough for your assets? |
| ☐ | Do you have rental reimbursement and towing or roadside coverage? |
| ☐ | Is your insurer's claim number and app saved on your phone? |
| ☐ | Is your proof of insurance in the car or on your phone? |
A safe-driving note
Insurance pays for damage; it can't prevent it. Slow down on ice, leave extra following distance, watch for deer at dawn and dusk, and keep a winter kit in the car. Avoiding a claim also keeps it off your record.
Related Minnesota guides
- Minnesota home and auto insurance cost guide
- Why Minnesota car insurance costs rose, and what drivers can compare
- Minnesota no-fault auto insurance explained
Compare auto quotes before winter
If you are reviewing coverage before winter, BetterSured reads the declarations page you upload so quotes match your current limits and deductibles, then vetted local independent brokers compete to quote that coverage. Brokers pay BetterSured for these requests, your details go only to the brokers who quote you, and a lower price is not guaranteed.
Related guides
Inflation Guard Endorsement: Protecting Your Home Against Rising Rebuild Costs
Minnesota No-Fault Auto Insurance Explained: PIP, Minimums, and What It Covers
What Is Loss Assessment Coverage? Protecting Yourself from HOA Special Assessments
Does Getting a Dog Raise Your Home Insurance? What Dog Owners Should Know